Warm but Idle: The Hidden Cost of Mothballed Oil and Gas Equipment Across America's Production Landscape
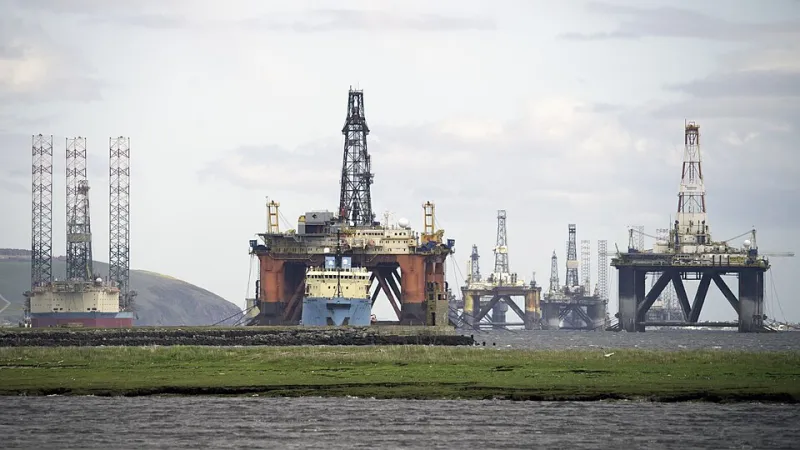
Photo: Michael Elleray from England, United Kingdom, CC BY 2.0, via Wikimedia Commons
The Arithmetic of Anticipation
Somewhere between the optimism of a commodity price rebound and the discipline required to manage a balance sheet, a growing number of US oil and gas companies have landed in an uncomfortable middle ground. Drilling rigs sit stacked in yards across West Texas and the Bakken. Modular processing facilities remain on standby at sites where wellhead economics no longer justify full operations. Separation equipment—expensive, specialized, and depreciating—occupies acreage without generating a barrel of production.
This is not a new phenomenon, but its scale has expanded meaningfully over the past several years. Industry estimates suggest that the value of mothballed upstream and midstream equipment currently sitting in various states of preservation across the United States runs well into the tens of billions of dollars. What was once a cyclical management tool has, for many operators, become a structural feature of how they approach capital and asset strategy.
The central question is whether this represents rational optionality or a slow-motion capital efficiency problem that the sector has yet to fully reckon with.
Why Companies Choose the Middle Path
The decision to mothball rather than decommission is rarely made carelessly. Operators weigh a specific set of trade-offs when a production asset becomes uneconomic or when drilling activity is suspended. Full decommissioning—particularly for offshore platforms, complex processing facilities, or environmentally sensitive onshore sites—carries substantial costs in permitting, remediation, and regulatory compliance. In many cases, those decommissioning costs rival or exceed the residual book value of the equipment itself.
Keeping assets in warm standby, by contrast, requires ongoing expenditure for maintenance, corrosion prevention, staffing, and insurance—but avoids triggering those larger exit costs immediately. More importantly, it preserves optionality. If West Texas Intermediate recovers to a level that makes marginal acreage viable again, or if a strategic buyer emerges for an idled facility, the asset can be reactivated rather than rebuilt from scratch.
For companies managing multi-year capital programs, this logic has genuine merit. Reactivating a stacked rig typically costs a fraction of procuring and mobilizing a new one. The same principle applies to gas processing plants and produced water handling infrastructure. When price cycles are the primary variable driving inactivity—rather than geological depletion or permanent market displacement—mothballing is a defensible strategy.
The Confidence Signal Hidden in the Numbers
What makes the current inventory of idle US petroleum equipment analytically interesting is what it implies about operator expectations. Mothballed assets represent a revealed preference: companies are signaling that they believe conditions will improve sufficiently within a defined horizon to justify the carrying cost of preservation. If they did not hold that belief, the rational move would be to write down the assets, decommission where required, and redeploy the capital elsewhere.
The fact that so much equipment remains in suspension suggests that a meaningful portion of the US upstream sector is operating with a medium-term price recovery thesis still intact. Operators are, in effect, paying a daily option premium—in the form of maintenance and holding costs—to retain the right to return to production without incurring full rebuild expenses.
But that calculus is sensitive to time. The longer assets sit idle, the more that carrying cost accumulates. Equipment that has been stacked for two or three years begins to require more intensive reconditioning before reactivation. Skilled personnel who once operated those facilities move on, and rehiring or retraining adds to the effective restart cost. At some point, the economics of warm standby begin to converge with the economics of full decommissioning—and the optionality premium becomes harder to justify.
Investor Scrutiny and the Balance Sheet Problem
Capital markets have grown more attentive to this dynamic. Institutional investors, particularly those with explicit energy transition mandates or return-on-capital benchmarks, are pressing US oil and gas companies for greater transparency around idle asset carrying costs and the specific conditions that would trigger either reactivation or write-down decisions.
For independent operators with tighter balance sheets, the pressure is more acute. A mid-sized producer carrying $300 million in mothballed infrastructure on its books—while servicing debt and managing active production costs—faces a different set of constraints than an integrated major with diversified cash flows. The idle asset line item can become a source of concern for lenders evaluating reserve-based lending facilities, particularly when commodity price assumptions used in asset valuations diverge from current market realities.
Several analysts tracking US upstream operators have noted an uptick in impairment charges related to idled equipment over the past 18 months, suggesting that some companies are beginning to recalibrate their recovery assumptions and accept the accounting consequences. Whether this represents the leading edge of a broader reckoning or an isolated adjustment remains to be seen.
Regional Concentration and Infrastructure Implications
The geography of mothballed capacity is not uniform. The Permian Basin, despite remaining the most active US producing region, contains pockets of stacked equipment where acreage proved less productive than anticipated during the pre-2020 drilling surge. The Haynesville and Marcellus plays have seen processing and compression assets idled as natural gas price volatility disrupted development economics. In mature conventional basins across the mid-continent and California, aging infrastructure sits in preservation as operators weigh whether enhanced recovery investments can generate sufficient returns.
Offshore, the picture is particularly complex. Gulf of Mexico operators managing aging fixed platforms face decommissioning liabilities that run into the hundreds of millions per structure. The incentive to delay is strong, but regulatory frameworks enforced by the Bureau of Safety and Environmental Enforcement are tightening around abandonment timelines, particularly for structures that have exceeded their original design life.
The regional concentration of idle equipment also has implications for local service sector employment and supply chain dynamics. Oilfield services companies—which provide the labor and specialized tools required for both maintenance and reactivation—must make their own workforce and investment decisions based on uncertain demand signals from operators who may or may not return idled assets to service.
What Reactivation Would Actually Require
For the stranded capacity to return to productive use at scale, several conditions would need to align simultaneously. Sustained price improvement above breakeven thresholds for the relevant asset class is the most obvious prerequisite. But beyond commodity price, operators would need confidence in regulatory stability, access to capital at favorable terms, and available oilfield services capacity—which itself has tightened as the services sector rationalized its own workforce and equipment fleets during the downcycle.
The interdependency of these factors means that even a significant price rally does not automatically unlock mothballed capacity. The lag between a price signal and meaningful production response from idled assets is longer than many market observers assume, and that lag has lengthened as the institutional knowledge embedded in experienced field crews has dispersed.
A Metric Worth Watching
For industry professionals monitoring US petroleum market conditions, the trajectory of mothballed asset inventories deserves more analytical attention than it typically receives. It functions as a proxy for operator confidence, a leading indicator of potential supply response, and a measure of capital efficiency across the sector. When companies begin systematically writing down idle equipment rather than maintaining it, that signals a genuine shift in recovery expectations—one with implications for future production capacity and industry structure alike.
The billions currently held in warm standby represent, in aggregate, a large and underappreciated bet on the medium-term future of US oil and gas demand. How that bet resolves will say as much about the sector's strategic direction as any earnings call or capital budget announcement.