Infrastructure at the Edge: Mapping the US Petroleum Assets Most Vulnerable to Permanent Write-Down
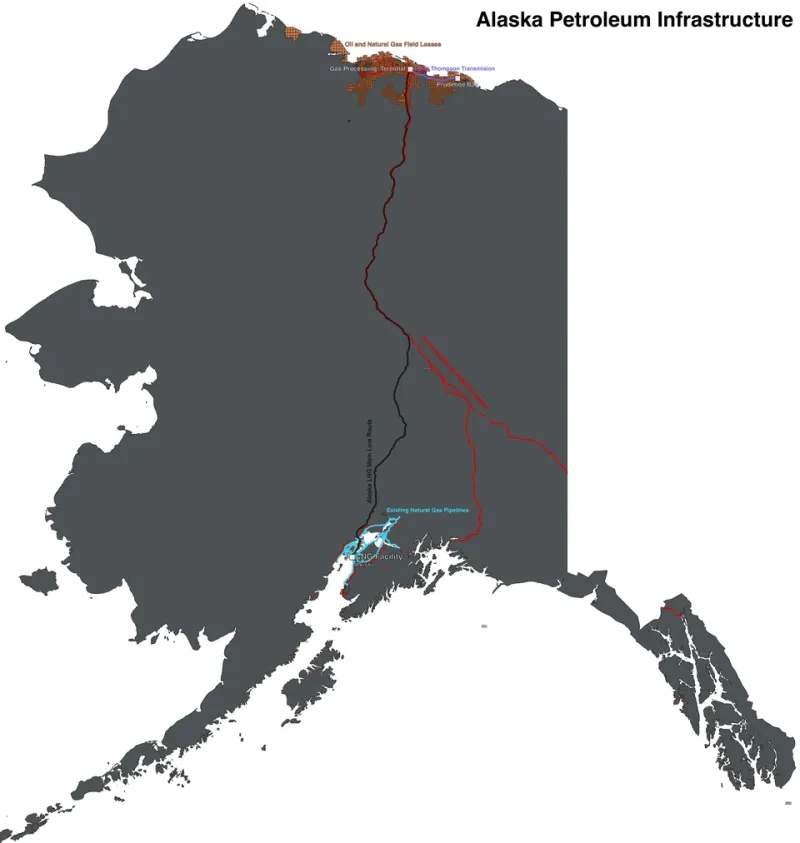
Photo: Wikideas1, CC0, via Wikimedia Commons
The conversation around stranded assets in the US petroleum sector has, for years, centered almost exclusively on proved reserves—hydrocarbons that may never be extracted if prices remain unfavorable or regulatory conditions tighten. That framing, while legitimate, has drawn attention away from a more immediate and arguably more tractable problem: the physical infrastructure already built, already capitalized, and already showing signs of economic distress.
Gathering systems, compressor stations, tank farms, and midstream processing facilities represent hundreds of billions of dollars in deployed capital across the continental United States. Not all of it will survive the next sustained market downturn. The question facing investors, operators, and lenders is not whether write-downs are coming—it is which assets will be written down first, and by how much.
The Utilization Gap: Where the Numbers Tell the Clearest Story
Operational utilization rates offer one of the most reliable early indicators of infrastructure at risk. When a gathering system or processing facility operates consistently below 60 percent of nameplate capacity, the economics of continued operation become difficult to justify against fixed maintenance and staffing costs. According to survey data compiled by PetroMar Survey across multiple US producing regions, a meaningful segment of midstream gathering infrastructure in mature basins—particularly in portions of the Anadarko, Arkoma, and Illinois Basin plays—is currently operating in that vulnerable range.
The situation is more nuanced in high-activity areas like the Permian Basin and the DJ Basin, where throughput volumes remain elevated. However, even in prolific regions, edge-of-system assets—smaller lateral gathering lines serving declining legacy wells—face accelerating volume attrition as production from those wellbores diminishes. Once throughput drops below the threshold required to cover operating costs, operators face a binary choice: subsidize the infrastructure from other revenue streams or begin abandonment proceedings.
For publicly traded midstream companies, this dynamic is already showing up in footnotes to financial statements, where impairment charges on gathering and processing segments have become more frequent over the past three fiscal years.
Compressor Stations: The Overlooked Liability
Of all the infrastructure categories examined in this analysis, compressor stations may represent the most underappreciated source of future write-downs. These facilities are highly capital-intensive to maintain, require specialized labor, and are often tied contractually to specific well pads or gathering systems. When the upstream production they serve declines, compressor stations cannot easily be redeployed to other locations without significant additional expenditure.
Engineering assessments reviewed for this report indicate that a substantial portion of compressor infrastructure installed during the shale buildout of 2010–2019 is now approaching the midpoint of its operational lifespan. Deferred maintenance—a widespread response to the 2020 price collapse—has accelerated effective aging on a portion of this fleet. When operators weigh the cost of refurbishment against the remaining productive life of the wells being served, the economic case for continued investment weakens considerably.
In regions where natural gas prices have remained structurally depressed, such as the Haynesville Shale's peripheral acreage and parts of the Fayetteville play, abandonment of compressor infrastructure is no longer a hypothetical scenario. It is already occurring, often without formal public disclosure.
Tank Farms and Crude Storage: Regional Exposure Varies Sharply
Crude oil storage infrastructure presents a more regionally differentiated risk profile. Tank farms located along major pipeline corridors—Cushing, Oklahoma being the most prominent example—retain strategic value tied to their position within the broader logistics network. Utilization at these hubs fluctuates with inventory cycles but rarely falls to levels that threaten long-term economic viability.
The more exposed assets are the smaller, isolated tank battery installations serving individual lease operations in mature producing states such as Kansas, Wyoming, and the Appalachian region. These facilities often serve conventional wells with declining production rates, and their economic case depends entirely on continued upstream activity at the connected wellbores. Financial modeling conducted for this analysis, using a base-case WTI price assumption of $62 per barrel and a stress scenario at $48 per barrel, suggests that a meaningful percentage of isolated lease storage infrastructure in these regions crosses into negative net present value territory within a five-year horizon under the stress scenario.
At $48 per barrel, the economics do not support continued maintenance expenditures on infrastructure serving wells producing fewer than 10 barrels per day—a threshold that encompasses a surprisingly large share of conventional production in America's older basins.
Processing Facilities: Scale Determines Survival
Natural gas processing plants demonstrate perhaps the clearest relationship between scale and survival probability. Facilities with throughput capacity above 200 million cubic feet per day generally possess the operational leverage to weather volume fluctuations and commodity price cycles. Smaller plants—particularly those below 50 MMcf/d—face a much steeper risk curve.
Survey respondents representing independent midstream operators consistently identified subscale processing facilities as the most likely candidates for consolidation or closure over the next decade. Several operators noted that NGL price volatility has compressed the margin cushion that historically made smaller processing facilities economically viable. When ethane rejection becomes economically necessary—as it has during multiple periods over the past five years—the revenue case for operating a small, older processing plant deteriorates rapidly.
The geographic concentration of at-risk processing infrastructure skews toward the Mid-Continent and select Appalachian sub-plays, where plant vintage, throughput scale, and NGL market access combine to create compounding vulnerabilities.
Capital Allocation Implications for Investors and Lenders
For investors holding equity or debt positions in companies with significant midstream or field infrastructure exposure, the central analytical task is disaggregating asset portfolios by utilization trajectory, replacement cost, and price-threshold sensitivity. Aggregate valuations that treat all infrastructure as homogeneous obscure the wide dispersion in abandonment risk across individual asset categories and geographies.
Lenders, particularly those extending credit against midstream collateral, face a related challenge. Traditional asset-based lending frameworks were calibrated during periods of volume growth and do not fully account for the possibility of rapid utilization decline in assets serving mature upstream production. Covenant structures that rely on throughput-based coverage ratios may provide less early warning than historical experience would suggest.
The implication is not that capital should exit the sector wholesale. It is that the sector requires far more granular risk assessment than most current analytical frameworks provide. Assets positioned on major transportation corridors with diversified throughput sources occupy a fundamentally different risk category than isolated, single-source infrastructure serving declining conventional production.
The Write-Down Timeline
Based on the combination of utilization data, engineering life assessments, and price-threshold modeling reviewed for this analysis, the most likely sequence of material write-downs over the next five to ten years runs as follows: isolated conventional-field gathering systems and tank batteries in mature basins lead the cycle, followed by subscale processing plants in the Mid-Continent and Appalachia, followed by compressor infrastructure tied to declining shale laterals in the outer portions of major plays.
The aggregate capital at risk across these categories is substantial. Conservative estimates, based on asset registry data and depreciated replacement cost methodologies, place the figure in the range of $40 billion to $70 billion across the continental US—with the upper bound reflecting a sustained low-price environment persisting beyond 2028.
For industry professionals making capital allocation decisions today, the data argues for deliberate scrutiny of infrastructure exposure, particularly in portfolios with significant conventional or marginal-acreage positions. The write-downs, when they arrive, will not be evenly distributed.