Sorting the Serious from the Symbolic: A Capital Allocation Analysis of US Oil Companies Pursuing Hydrogen
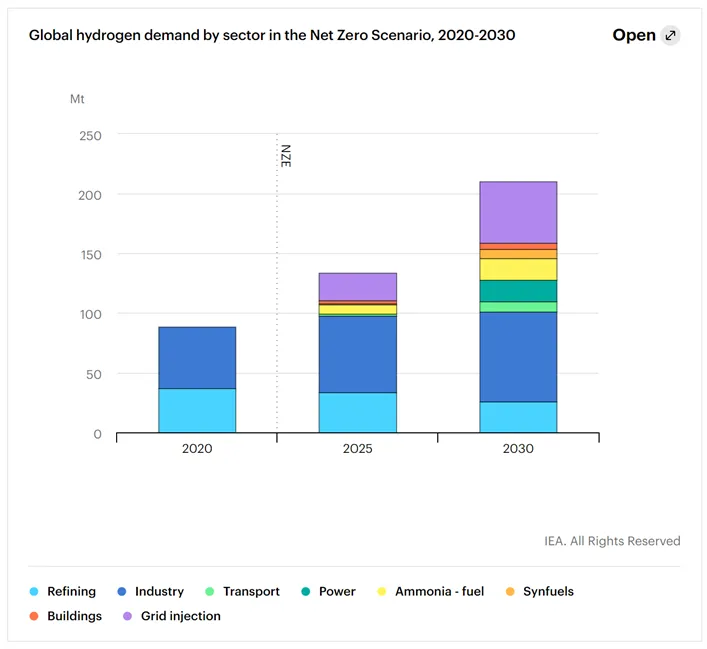
Photo: IEA, CC BY-SA 4.0, via Wikimedia Commons
The word "hydrogen" now appears in the strategic communications of nearly every major US petroleum company. It surfaces in investor presentations, sustainability reports, and earnings calls with a frequency that, taken at face value, would suggest the industry is on the cusp of a sweeping energy transformation. The reality, as capital allocation data and project timelines reveal, is considerably more complicated. A rigorous look at who is spending what, where, and toward what end separates a small cohort of genuinely positioned operators from a much larger group engaged in what amounts to strategic signaling with limited commercial follow-through.
The Anatomy of a Hydrogen Commitment
Not all hydrogen announcements carry equivalent weight. The industry has learned, through several cycles of energy transition rhetoric, to distinguish between a memorandum of understanding and a final investment decision—between a pilot facility and a commercial-scale asset. Applying that discipline to the current hydrogen landscape is essential for any professional attempting to assess where durable value may emerge.
Among the US integrated majors, capital directed toward hydrogen remains a modest fraction of total upstream and downstream expenditure. Public disclosures from companies including ExxonMobil and Chevron indicate that hydrogen-related investment, while growing in absolute terms, has not yet achieved the scale necessary to represent a material contributor to future earnings. ExxonMobil's announced hydrogen hub ambitions in the Gulf Coast region—anchored by its Baytown, Texas complex—represent the most substantive commitment among domestic majors, with the company citing its existing industrial infrastructure and proximity to petrochemical demand as structural advantages. Chevron, by contrast, has distributed its hydrogen exposure across a broader portfolio of smaller equity positions and partnerships, a strategy that preserves optionality but limits near-term revenue contribution.
Independent operators present an even more fragmented picture. Several mid-size companies have attached hydrogen language to existing carbon capture or refinery upgrade projects, effectively relabeling incremental investments rather than committing fresh capital to purpose-built hydrogen production.
The Blue versus Green Divide
Understanding the hydrogen strategies of petroleum companies requires clarity on the production pathway under discussion. Blue hydrogen—produced from natural gas with carbon capture and storage—is the variant most naturally suited to companies with existing gas production, pipeline access, and geological storage resources. Green hydrogen, generated through electrolysis powered by renewable electricity, demands an entirely different asset base and cost structure.
For US oil and gas companies, the blue hydrogen pathway offers an obvious point of entry. The domestic natural gas supply position is strong, and several basins—particularly along the Gulf Coast—sit above geological formations suitable for CO2 sequestration. The 45Q tax credit, expanded under the Inflation Reduction Act, has materially improved the economics of carbon capture, making blue hydrogen projects more financeable than they were three years ago. The production tax credit provisions for clean hydrogen under Section 45V have added further incentive, though the regulatory guidance surrounding lifecycle emissions thresholds has introduced uncertainty that continues to delay final investment decisions.
Green hydrogen economics remain challenging for most petroleum companies. The capital intensity of electrolysis capacity, combined with the cost of renewable power procurement, produces a levelized cost of hydrogen that is difficult to reconcile with current market pricing outside of niche applications. Companies announcing green hydrogen ambitions without a credible renewable power cost advantage—whether through co-located generation assets or long-term power purchase agreements at competitive rates—are unlikely to build commercially viable projects.
Geographic Advantages That Actually Matter
Location is not incidental to hydrogen economics—it is frequently determinative. The Gulf Coast corridor, stretching from Corpus Christi through Houston to the Louisiana industrial complex, possesses a concentration of advantages that no other US region can match: existing hydrogen pipeline infrastructure, dense industrial demand from refining and petrochemicals, deepwater port access for potential export, and subsurface storage geology. Companies with established operational footprints in this corridor begin with a structural lead that is difficult for newcomers to replicate quickly.
The Department of Energy's Regional Clean Hydrogen Hubs program, which designated seven hub recipients in 2023, has introduced a second geographic dimension. Hub designation brings federal co-investment and, more importantly, the prospect of demand aggregation across multiple industrial end-users. Companies with assets or partnership positions within these hub geographies—particularly the Gulf Coast hub and the Heartland hub spanning the midcontinent—are better positioned to access the scale necessary for economic hydrogen production and distribution.
Outside these corridors, the commercial case for hydrogen investment by petroleum companies weakens considerably. Announcements from operators in regions without industrial demand clusters, storage geology, or existing pipeline infrastructure should be evaluated with appropriate skepticism.
Quantifying the Timeline Problem
Perhaps the most underappreciated challenge facing petroleum companies pursuing hydrogen is the mismatch between announcement timelines and commercial reality. Project development cycles for large-scale hydrogen and carbon capture infrastructure routinely extend eight to twelve years from concept to full operation, encompassing permitting, engineering, financing, and construction phases that cannot be compressed without accepting elevated execution risk.
This timeline creates a structural tension with the investor relations imperative to demonstrate near-term progress. The result, observed repeatedly across the sector, is a proliferation of announcements tied to early-stage milestones—feasibility studies completed, partnerships signed, site options secured—that generate press coverage without advancing projects toward revenue generation. Investors and industry analysts who track capital expenditure against announced project pipelines will note that the ratio of commitments to completions remains unfavorable across the sector as a whole.
The companies most likely to convert hydrogen ambitions into commercial operations are those that have moved beyond announcement into permitting and front-end engineering design, secured offtake agreements with creditworthy industrial customers, and demonstrated access to project financing at terms consistent with the risk profile of a first-of-kind facility.
Separating Durable Strategy from Narrative Management
The petroleum industry has navigated energy transition pressures before, and institutional memory includes examples of technology pivots—fuel cells, biofuels, coal gasification—that absorbed capital without generating proportionate returns. Hydrogen may ultimately prove different in scale and durability, but the analytical framework for evaluating corporate commitments should remain consistent: examine capital deployed relative to capital announced, assess whether the asset base and geographic position support the claimed strategy, and evaluate whether the business model generates returns at realistic hydrogen pricing.
By those measures, the current field of US petroleum companies pursuing hydrogen narrows considerably. A handful of operators—those with Gulf Coast infrastructure, CO2 storage access, and demonstrable progress toward final investment decisions—have assembled the prerequisites for genuine participation. The remainder, whatever their communications may suggest, are more accurately described as monitoring a market they may choose to enter if economics improve, or exit if investor attention shifts.
For energy sector professionals allocating analytical resources and tracking competitive positioning, the distinction matters. Capital follows credibility, and credibility in hydrogen, as in every other segment of the petroleum business, is ultimately built on assets, not announcements.