Load Growth on Paper: Testing the Data-Center Gas Demand Story Against Signed Contracts
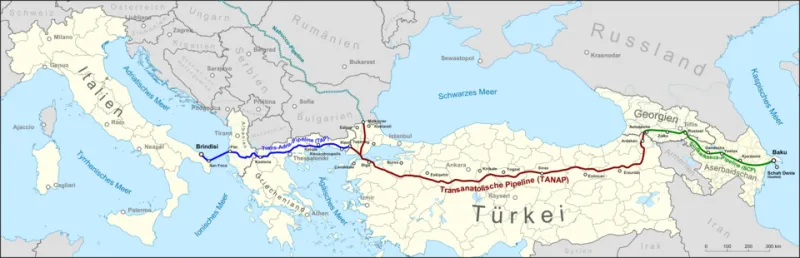
Photo: Pechristener File:Nabucco West Route.jpg: PowerPerson File:BTC-Pipeline.png: Devil_m25, Antemister, CC BY-SA 2.0, via Wikimedia Commons
The data-center narrative has become the most reliable demand story in US energy markets, and it is delivered with unusual confidence. Project announcements, utility integrated resource plans, and consultant forecasts now routinely present multi-billion-cubic-foot-per-day increments of new gas demand by the early 2030s. What is far less discussed is how much of that demand has actually been contracted for.
That distinction matters enormously to anyone making capital, procurement, or risk decisions on the strength of the forecast. Announced capacity is a statement of intent by a developer. A precedent agreement is a statement of obligation by a shipper. The gap between the two is where most of the uncertainty lives.
The Forecast, and the Contract Behind It
Forecasts are useful, but they are not commitments. A hyperscaler's press release describing a campus of a given nameplate capacity tells an analyst almost nothing about the load profile, the interconnection status, the backup configuration, or the gas transportation arrangement behind it. Each of those variables can move the implied gas burn by a factor of two or more.
The practical result is that headline demand figures often combine projects at wildly different stages of maturity into a single number. A campus with a signed transportation agreement, an air permit, and a filed pipeline certificate is treated identically to a project that exists as a land option and a press release. They should not carry the same weight.
Capacity Is Not Consumption
Nameplate megawatts are a poor proxy for gas burn. Data-center load factors vary widely depending on tenant mix, cooling design, and redundancy requirements, and firm loads in the 50 to 70 percent range of nameplate are common. Behind-the-meter arrangements, on-site generation with dual-fuel capability, and interruptible service agreements all change the gas consumption equation without changing the headline capacity figure.
Timing compounds the problem. A significant share of announced capacity carries in-service targets in the late 2020s and early 2030s, which means the demand is not merely uncertain in volume but deferred in date. Deferred demand is especially sensitive to interest rates, equipment lead times, and power market prices at the moment of final investment decision.
Precedent Agreements as the Real Ledger
Pipeline development provides the most reliable public evidence of committed demand. To justify a new expansion, a pipeline must typically secure precedent agreements from shippers covering a substantial share of capacity. Those agreements surface in Federal Energy Regulatory Commission filings, sometimes with volumes and terms redacted, but frequently with enough disclosure — total contracted capacity, contract duration, shipper creditworthiness — to be useful.
When announced generation capacity and contracted transportation capacity are placed side by side, the picture is uneven. In several corridors, contracted takeaway capacity is expanding at a measured pace that implies incremental demand well below the aggregate of announced projects. That is not evidence of a bust. It is evidence that developers are staging commitments rather than signing them all at once.
Three Tests for Durable Demand
Is the load firm and the counterparty creditworthy? Interruptible service contracts and non-investment-grade offtakers carry a very different demand profile than twenty-year firm transportation with a large, rated shipper. Analysts should insist on the distinction rather than netting the categories together.
Does the infrastructure have a date and a docket? A pipeline with a filed certificate application and a stated in-service window is a materially stronger signal than a project described as under development. Permission to build is not the same as an obligation to flow, but it is a meaningful filter.
Is the demand incremental to the system? Some announced load represents a shift rather than an addition — a new campus replacing an older industrial user, or on-site generation displacing utility-supplied power. Incremental system demand is what ultimately shows up in storage draws and power burn.
What Would Change Our View
We would upgrade the demand story on evidence of three things: sustained growth in gas-fired generation burn in the relevant power markets, a rising volume of executed firm transportation contracts disclosed in pipeline filings, and utility resource plans that convert announced capacity into approved generation additions with corresponding gas supply arrangements.
Conversely, a widening gap between announced capacity and contracted transportation capacity over successive quarters would be the clearest warning that the demand curve is being built from announcements rather than obligations. For an industry that has repeatedly been burned by demand stories that peaked before the steel was set, that gap deserves more attention than the headline forecast.